The Croatian economy is expected to slow down significantly this year, but certain sectors are in a much better position than others. The energy sector stands out as the most promising sector in Croatia, while the textile industry is under increasing cost pressure, according to a new Coface report on opportunities and risks in the sectors of Central and Eastern Europe.
According to estimates from Coface, after a growth of 3.4 percent in Croatian GDP in 2025, this year the rate is expected to fall to 2.1 percent, and in 2027 it will accelerate again to 2.7 percent. Household consumption is still expected to be the main driver of economic growth, while tourism remains an important external stabilizer.
Coface gives the best prospects to the energy sector. Supporting factors include the expansion of the LNG terminal on Krk, energy transition projects funded by European money, and increased use of oil infrastructure related to Europe’s gradual withdrawal from Russian oil.
On the other hand, the textile industry is under pressure. It is burdened by strong wage growth, a very tight labor market, and higher costs of synthetic raw materials produced from oil derivatives.
Sectors Become More Important Than Borders
Croatia is not an exception in the increasingly pronounced separation of successful and vulnerable industries. One of the main conclusions of the Coface report Opportunities and Risks by Sectors for Central and Eastern Europe 2026 is that belonging to a certain sector today can affect the business results of companies more than the country in which they operate.
Coface analyzed 13 sectors in 13 countries of Central and Eastern Europe, and the metal and chemical industries most frequently appear among the vulnerable sectors. They are burdened by high energy costs, regulatory requirements, and increasingly strong foreign competition.
ICT is at the other end of the scale. It remains one of the most successful sectors in the region, supported by digitalization, a qualified workforce, and public investments. Construction, healthcare, defense-related industries, and digital transformation should receive additional incentives from programs funded by European Union funds.
– The difference between sectors today is greater than the difference between countries. Future success will depend less on overall economic growth and more on how effectively individual industries will adapt to changes in cost structures, technological transformation, and global competition – says Mateusz Dadej, regional economist at Coface for Central and Eastern Europe.
The “Chinese Shock 2.0” Is Coming
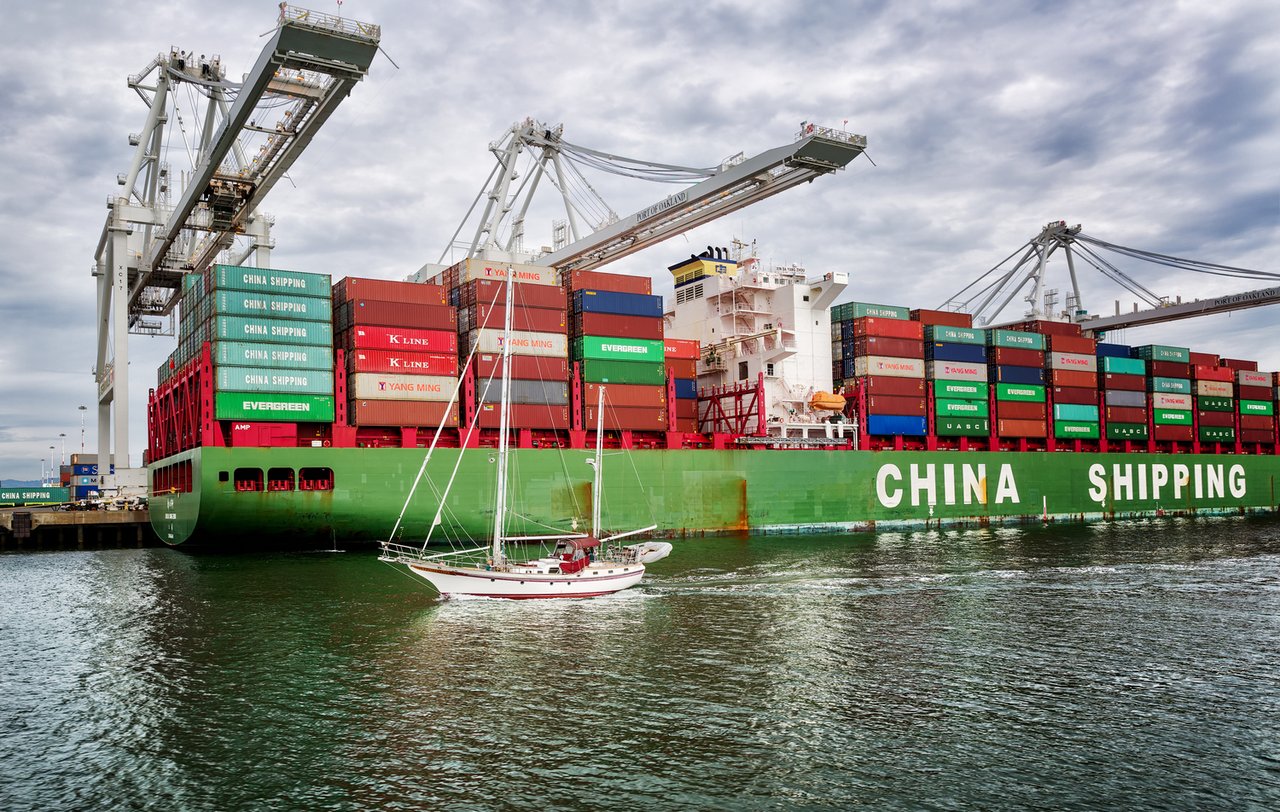
One of the reasons for the increasing differences among sectors is the strong growth of Chinese exports. Chinese imports to Central and Eastern European countries have increased by about 17 percent in the past year.
Coface describes this new wave of competition as “Chinese Shock 2.0”. Faced with weaker domestic demand, Chinese manufacturers are increasingly turning to export markets, especially Europe. The consequence is greater pressure on European manufacturers, their market shares, and profit margins.
Among the most exposed industries, Coface lists the automotive, chemical, and metal industries.
Additional problems are created by disruptions in maritime traffic through the Hormuz Strait, the consequences of which go beyond the energy market. The rise in oil and natural gas prices spills over into the prices of fertilizers, aluminum, and petrochemical products, increasing costs along supply chains and reinforcing inflationary pressures.
Despite these risks, Coface expects only a slight slowdown in the economies of Central and Eastern Europe. Regional growth is expected to fall from 2.1 percent in 2025 to 2 percent this year, and then accelerate again to 2.3 percent in 2027.
An important support should be European funds. Investments financed through the Recovery and Resilience Facility (RRF) and the SAFE program should support construction, healthcare, digitalization, and infrastructure, alleviating some of the consequences of geopolitical uncertainty.
From Polish ICT to Slovak Automotive Industry
Differences among individual economies in the region remain significant. Poland is expected to remain among the fastest-growing large economies in the European Union, with growth rates of 3.6 percent this year and 3.7 percent next year. The main support is ICT, aided by strong demand, investments from the Recovery and Resilience Facility, and a large number of highly educated IT professionals. Construction, on the other hand, is at increased risk due to slower utilization of European funds, weak demand, and rising insolvencies.
Romania is in a significantly more difficult situation. Coface expects the economy to enter a recession in 2026 under the influence of fiscal consolidation, while growth of 1.6 percent is expected to return in 2027. The pharmaceutical industry shows resilience, but retail is affected by higher VAT, the abolition of energy subsidies, falling real wages, and delays in larger purchases.
In Hungary, growth is expected to accelerate thanks to personal consumption and the anticipated influx of European funds. Retail is among the more promising sectors, while the chemical industry continues to suffer from weak demand, high energy dependence, and weaknesses in the automotive and construction industries.
Slovakia is expected to grow only 0.9 percent this year, but its automotive industry remains among the most promising sectors. Coface highlights record vehicle exports, the expansion of electric and hybrid vehicle production, and the start of operations at the new Volvo factory in Košice. Retail is simultaneously pressured by fiscal consolidation, higher taxes, and rising inflation.
Slovenia Relies on Pharmaceuticals
The Slovenian economy is expected to accelerate to 2.5 percent this year and grow 1.8 percent in 2027. The pharmaceutical industry remains among the most resilient due to strong exports, an increase in the trade surplus, and greater demand for biological drugs and weight-loss medications.
However, the Slovenian automotive industry is undergoing a transformation due to the shift to electric vehicles, increasing competition from Chinese manufacturers, and higher operating costs compared to other countries in the region.
In Austria, the picture is similar to the broader regional trend: ICT is strengthening, while the metal industry is weakening. Austrian GDP is expected to grow only 0.5 percent this year, while the metal industry is affected by weak business sentiment, declining production, and renewed increases in energy costs. Coface therefore classifies it in the very high-risk category. At the same time, ICT records double-digit growth in new orders and improved business confidence.
The Czech Republic is gradually recovering, primarily thanks to household consumption, rising real wages, and a decrease in the savings rate. Retail benefits from this, while the metal industry remains at increased risk. Steel production in the Czech Republic has halved over the last decade, and the industry continues to be pressured by high energy and carbon costs.
Construction Strengthens in Bulgaria, ICT in Lithuania
The Bulgarian economy is expected to slow down from 3.1 percent growth in 2025 to 2.7 percent this year and 2.5 percent next year. Construction stands out there as the most promising sector due to rising purchasing power, urbanization, favorable financing costs, and an increase in the number of building permits. The metal industry remains under pressure from high energy prices, the abolition of electricity subsidies, and weak demand in civil engineering.
Lithuania is expected to remain among the faster-growing economies in the region, with growth of 3 percent this year and 2.9 percent next year. It is led by ICT, along with a strong electronics industry, an internationally competitive laser and photonics sector, and the development of software, fintech, and other digital services. Transport, on the other hand, is affected by geopolitical tensions with Belarus, disrupted routes, a shortage of drivers, and higher costs.
In Latvia, the wood industry shows resilience due to the stabilization of demand and the development of higher value-added products, while transport is exposed to weaker demand, problems with the national airline, and fluctuations in fuel prices.
The Estonian pharmaceutical industry also proves resilient, supported by an aging population, increased drug consumption, and a developed digital health infrastructure. The chemical industry, however, remains burdened by low capacity utilization, dependence on energy-intensive processing of oil shale, and rising costs associated with European climate policy.
In Serbia, the paper industry stands out among the more promising sectors, aided by demand for packaging, growth in e-commerce, and a shift towards more sustainable fiber-based packaging. According to Coface, energy is one of the main weaknesses due to a persistent energy trade deficit and high dependence on imports of Russian oil and gas.
All this shows why the rate of economic growth itself increasingly says less about how individual companies will perform. For businesses, it becomes more important which sector they are in, how exposed they are to energy prices and Chinese competition, and whether they can leverage technological transformation and the new European investment cycle.