Home / Business and Politics / Government Changes Taxes: Companies, Flat-Rate Taxpayers, and Renters Pay More

Government Changes Taxes: Companies, Flat-Rate Taxpayers, and Renters Pay More

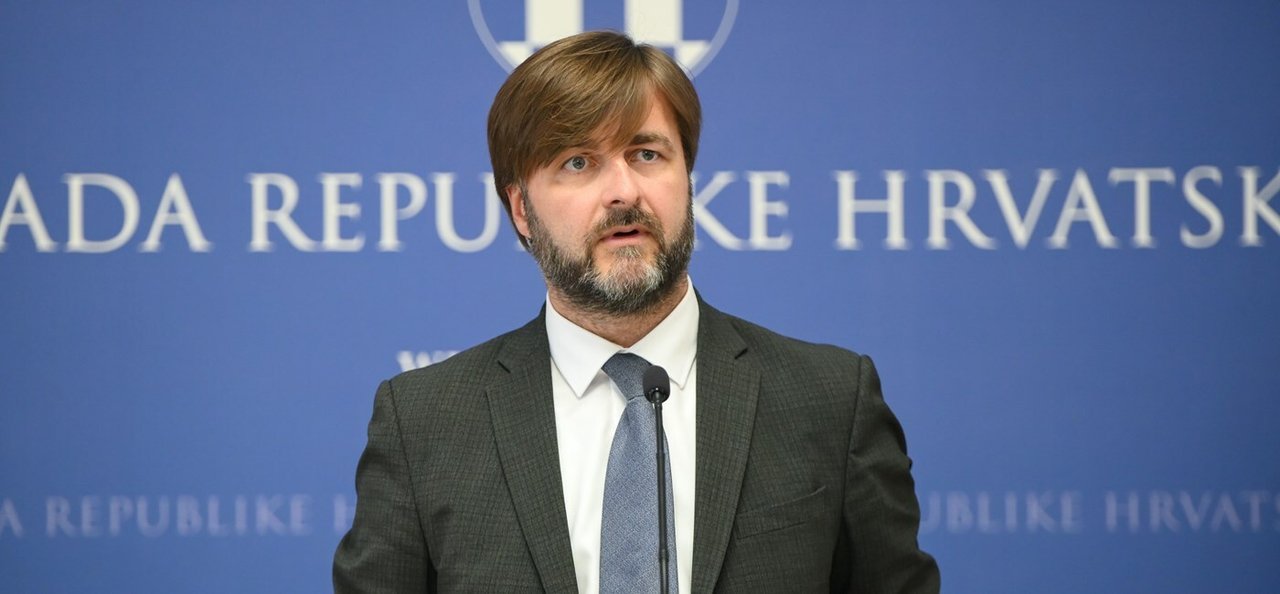
<p>Tomislav Ćorić</p>
Tomislav Ćorić / Image by: foto

On Thursday, the government submitted proposals for tax changes to the Parliament, introducing taxation on excessive profit margins of large and medium-sized companies, as well as changes in the taxation of pensions, flat-rate businesses, short-term rentals in tourism, and the VAT Act, which is being aligned with the new EU directive.

The government proposes the introduction of a profit tax on excessive profit margins as a one-time anti-inflation measure for the tax period of 2026. The tax would apply to approximately 1,800 large and medium-sized entrepreneurs, whom the government estimates could influence inflation growth, provided that more than 50 percent of the value of their goods and services is generated in the Croatian market.

– The logic we are following is that in this way we discourage primarily those who are exploiting inflationary movements caused by exogenous factors and the fact that the escalation that occurred at the beginning of the year conditioned very high inflation rates, so they do not exploit it to increase the prices of their products, i.e., to collect excessive margins – said Deputy Prime Minister and Minister of Finance Tomislav Ćorić, presenting the legislative proposal at the government meeting.

The profit margin will be calculated as the ratio of adjusted profit and income reported in the tax return. It will be considered excessive if in 2026 it is at least 15 percent higher than the average margin that the same entrepreneur achieved in the previous three years, from 2023 to 2025. A tax at a rate of 50 percent will be paid on the determined excess margin.

– I would like to point out that part of the amendments to the law concerning excessive trade margins, i.e., taxation, has already shown its preventive role in practice since we presented it, as there has been a sharp reduction in the growth of some prices. This means that those who understood what the provisions of the law would be, which will come into force on January 1 after being adopted by the Parliament, have carefully considered what prices they will set. Therefore, it seems to me that this reform has already shown its preventive effects even before it has been adopted – emphasized Prime Minister Andrej Plenković at the introductory part of the government session.

Changes in Income Taxation

The proposal for amendments to the Income Tax Act plans to abolish the taxation of pensions, or, as stated in the proposal, to increase the percentage of reduction from the previous 50 to 100 percent of the tax obligation on pensions, on which income tax is paid at a lower rate (monthly tax base up to 5,000.00 euros, or annual tax base up to 60,000.00 euros).

The government illustrates this with the example of a retiree with a pension of 800 euros. After applying a personal deduction of 600 euros, the tax base amounts to 200 euros, on which 40 euros of tax is calculated at a lower rate of 20 percent. This amount is now reduced by 50 percent for retirees, so the final tax obligation amounts to 20 euros. According to the proposed amendments, the retiree in this example will not pay income tax.

Regarding the tax treatment of ‘flat-rate taxpayers’, the first five tax brackets will be exempt from increased burdens, up to annual incomes of 40,000 euros. However, it is proposed to change the amount of recognized expenses for individuals whose self-employment is taxed flat-rate, so that recognized expenses gradually decrease with the increase in the amount of realized income through higher tax brackets, from 85 to 70 percent for individuals in the sixth tax bracket (income from 40,000.01 to 50,000.00 euros) and to 55 percent for individuals in the seventh tax bracket (income from 50,000.01 to 60,000.00 euros).

– These tax changes will not affect 83.4 percent of our craftsmen. Likewise, all those flat-rate craftsmen who are in the upper two brackets, i.e., from 40 to 60 thousand euros, who believe that their deductible items should be higher, can start keeping business records and thus clearly address the real situation in their crafts – said Ćorić.
Increase in Flat-Rate Tax for Tourist Beds

An increase in the lower limit of prescribed ranges of flat-rate tax per bed, i.e., accommodation unit in a camp or accommodation unit in a Robinson-style accommodation for I. and II. category local self-government units according to the tourism development index is also planned, from 100 to 150 euros (I. category) and from 70 euros to 100 euros (II. category). Accordingly, changes in the amount of flat-rate tax are proposed in case the representative body of the local self-government unit does not make a decision for the mentioned categories, from 200 euros to 225 euros (I. category) and from 135 euros to 150 euros (II. category).

Among other things, the amendments to the law will stipulate that in the procedures for determining the disproportion of assets and reported income the tax obligation arises in the year in which it is determined during the procedure that there are grounds for taxation and that the Tax Administration can ex officio, based on the data it possesses, enter the taxpayer into the register of taxpayers.

The government will prescribe a new type of income and tax treatment for income generated from investments in assets recorded within the Croatian investment account. As emphasized, no income tax is paid on the mentioned income; however, in the case of non-fulfillment of the conditions prescribed by the regulation governing Croatian investment accounts, it is proposed to prescribe a new type of income from capital generated from investments in assets through the Croatian investment account, which would be taxed at a rate of 12 percent.

The proposal estimates that the financial effect of the exemption from income tax on pensions will reduce revenues in the budgets of local self-government units from income tax by about 180 million euros, while changes related to flat-rate taxation of self-employment will increase revenues of local self-government units by 23.5 million euros.

Changes in Contribution Payments for Flat-Rate Taxpayers

Amendments to the Contributions Act have also been submitted to the Parliament, proposing an increase in coefficients for calculating contributions for insured persons based on self-employment from which they determine flat-rate income tax from 0.4 to 0.45 for individuals in the sixth tax bracket (income from 40,000.01 to 50,000.00) and for individuals in the seventh tax bracket (income from 50,000.01 to 60,000.00) to 0.5.

For insured persons who will earn income from 40,000.01 to 50,000.00, the monthly contribution obligation will increase by 12.5 percent, and for insured persons who will earn income from 50,000.01 to 60,000.00, the monthly obligation will increase by 25 percent.

On this basis, it is expected that the state budget will receive approximately 3.8 million euros from contributions for pension insurance based on generational solidarity in 2027, revenues from contributions for health insurance will amount to 4.1 million euros, and revenues from contributions for pension insurance based on individual capitalized savings will amount to 1.3 million euros.

VAT Act Aligns with EU Directive

The proposed amendments to the Value Added Tax Act, on the other hand, align the government with the EU directive regarding VAT rules for the digital age, effective January 1, 2027.

As stated in the proposal submitted to the Parliament, the proposed amendments aim to improve existing provisions related to the One Stop Shop (OSS) and Import One-Stop Shop (IOSS) systems, through which entrepreneurs can report and pay VAT for services provided to non-taxable persons and for the sale of goods at a distance, for so-called online sales to citizens in the EU.

Among other things, it is intended to more precisely define the threshold of 10,000 euros for distance sales within the EU, and it is also proposed to raise the non-taxable amount for small-value gifts from 22 euros quarterly to 100 euros annually per recipient.

Tagged: