
Once again, geopolitics takes center stage. Donald Trump and China, who else? And a ceasefire in Gaza. On top of all this, we must add the issue of rising global public debt, falling purchasing power, the loss of value of major currencies, the potential collapse of France, and the rise in the prices of gold and silver to new record levels, and we get a weekly overview.
Industrial production decreased worldwide in September due to slowing economic activity in the U.S., weakening demand in China, and the ongoing U.S. trade war. Global crises, culminating in the rapidly rising public debt of the U.S., are leading towards a world “very similar” to that before World War II, according to investor and economic historian Ray Dalio. The American debt bomb threatens the entire monetary system. U.S. public debt is rising too quickly and has already reached 99 percent of GDP and is expected to exceed 116 percent by 2034, becoming a record high in American history. Rising debts are only part of the problem. The situation is exacerbated by increasing global conflicts and wealth inequality. The U.S. and other countries are heading towards civil war with irreconcilable differences, Dalio emphasizes.
Silver Follows Gold’s Rise
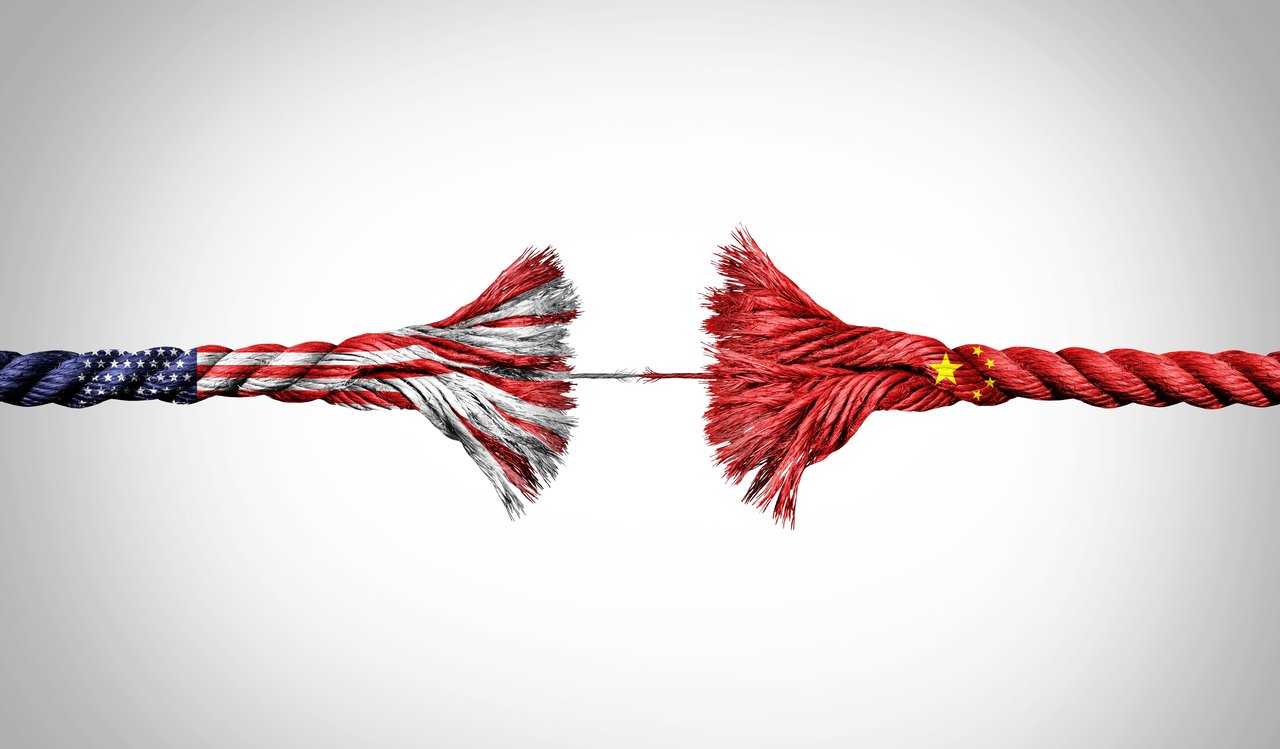
At the end of last week, China imposed stricter export controls on everything containing a certain level of rare metals and elements in goods. Specifically, under the new rule, global companies selling goods that contain trace elements from China (seemingly 0.1 percent or more of the product’s value) will need approval from Beijing. This rule will certainly raise additional tensions in the U.S.-China trade war and significantly impact supply chains. A headache for all procurement directors. The first industries to be affected will be automotive, solar panels, and chip manufacturing equipment and other products. China produces about 90 percent of rare elements in the world, and rare earth minerals are the “trump card” that China holds over the West.
Trump’s response is the introduction of an additional 100 percent tariff on China starting November 1, as well as restrictions on the export of all strategic software to China. The only hope left is the anticipated meeting between Trump and Xi, which could push the relations of the two countries towards a better future. Trump already softened his rhetoric towards China a bit on Sunday. We will see what happens during the week. This week, there will be no significant announcements as government institutions in the U.S. are not operating until further notice due to the failure to reach a budget agreement.
Central banks have crossed a symbolic threshold: for the first time in nearly three decades, their combined gold reserves exceed their holdings in U.S. Treasury bonds. This shift highlights a gradual diversification from dollar-denominated securities to tangible assets. Gold broke the record of $4,000/oz last week, driven by expectations of further interest rate cuts by the FED later this month and persistent demand for safe assets due to the current geopolitical situation. Goldman Sachs estimates the price of gold at $4,900/oz by the end of 2026. If this estimate proves accurate, fiat money will lose an additional 20 percent of its purchasing power.
Silver has outperformed the record growth of gold prices this year and could further surpass it. With a rise of 66 percent in 2025, silver has already far outpaced the growth of gold prices at 52 percent. The silver market has recorded a structural deficit for the fifth consecutive year since 2021, with global demand exceeding supply. Industrial use of silver is sharply increasing, driven by electric vehicles, artificial intelligence, and green technologies. Demand for industrial production is primarily driven by China, thanks to its massive manufacturing base and leadership in key sectors such as electronics, solar panels, and electric vehicles. Silver is a crucial component for weapon production.
Energy Prices Fall
On global markets, oil prices fell again last week, the second consecutive week, by about 3 percent, due to the escalation of the trade war between the U.S. and China, OPEC’s announcement of increased production, and the ceasefire in Gaza. Thus, the futures price of WTI oil fell below $60/bbl, and Brent below $65/bbl. These are their lowest levels since May. The escalation of the trade war between the U.S. and China could slow global economic growth, and thus demand for energy. Additionally, oil prices have slipped due to easing tensions in the Middle East. Representatives of Hamas and Israel signed a ceasefire agreement on Thursday, under which Hamas would release hostages it has held captive for more than two years, while Israeli armed forces would withdraw from Gaza and allow the entry of humanitarian aid convoys. The cessation of hostilities could mark the beginning of normalizing traffic, and thus the passage of tankers through the Red Sea and the Suez Canal. Furthermore, OPEC+ allies recently decided to increase production by 137,000 barrels per day in November, as well as in October.


