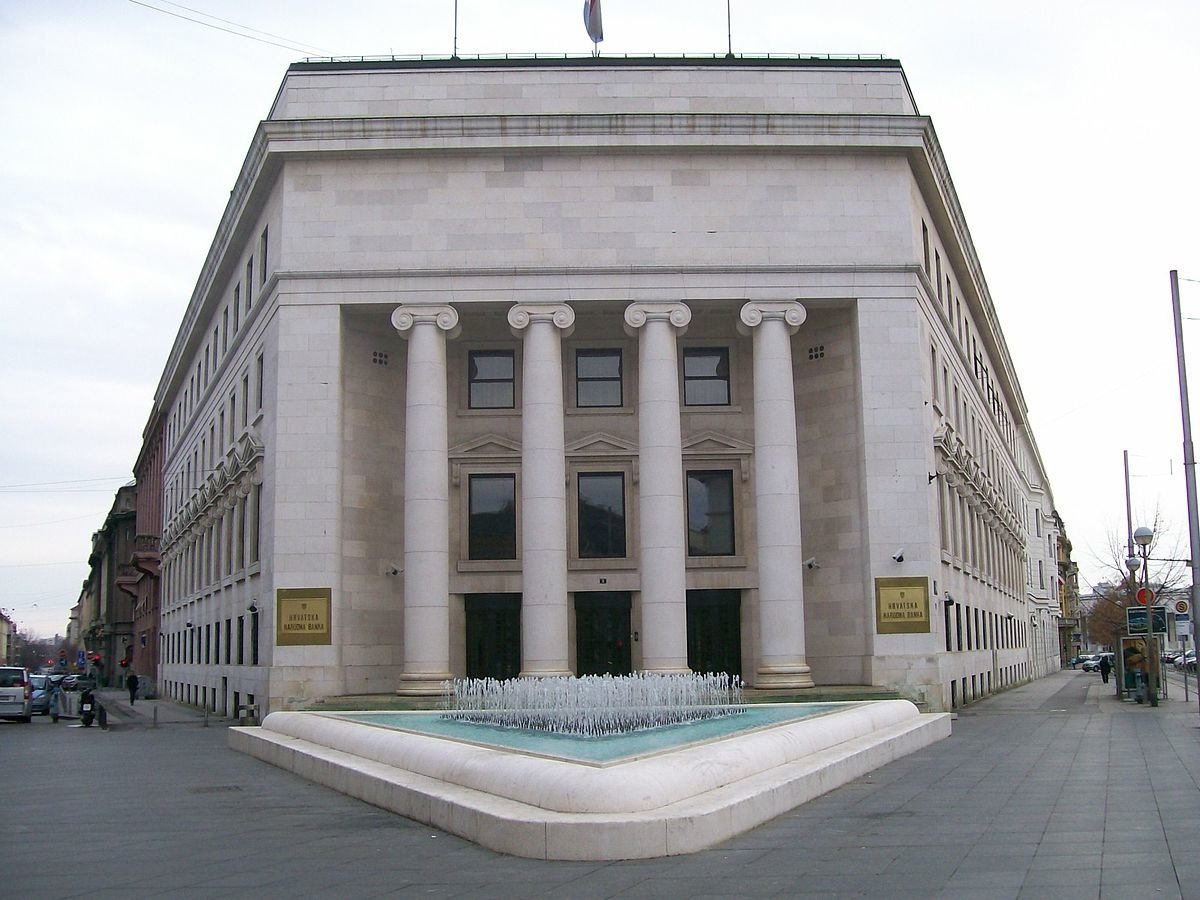
According to the first estimate by Eurostat, inflation measured by the Harmonized Index of Consumer Prices (HICP) significantly slowed down in November (to 5.5 percent from 6.7 percent in October). This was contributed by all major components of overall inflation. The decrease in energy price inflation in November to -4.1 percent from -0.7 percent in October is a result of the reduction in energy prices (primarily petroleum products) compared to the previous month, as well as the favorable base effect (due to the monthly increase in those prices in November last year when petroleum products became more expensive), stated the Croatian National Bank (HNB).
The average price of Brent crude oil on the global market in November was $83.7, which was 8.1 percent lower compared to October. The increase in crude oil prices on the global market following the outbreak of conflict in the Middle East in early October was short-lived, and crude oil prices have gradually fallen in recent weeks.
However, a possible increase in these prices due to geopolitical tensions still poses a significant risk for future inflation trends. Food price inflation (including alcohol and tobacco) slowed down in November to 7.7 percent from 8.6 percent in October, in conditions of reduced cost pressures, slowing growth of food producer prices, and a favorable base effect (due to a more pronounced monthly increase in food prices in the same month last year, which no longer affects the calculation of the annual food price inflation rate).
—
—
Core inflation (which excludes energy and food prices in its calculation) decreased in November to 6.8 percent from 7.5 percent in October, with inflation of both components slowing down (inflation of industrial product prices to 4.6 percent from 5.5 percent and services to 8.6 percent from 9.2 percent), in an environment of lower energy prices and other products used in the production of industrial goods and the provision of services. Core inflation remains elevated, primarily due to still high inflation in service prices, largely driven by domestic factors, namely inflationary pressures arising from wage growth and solid domestic demand.
Overall inflation measured by the national consumer price index, according to the first estimate by the DZS, slowed down in November to 4.7 percent from 5.8 percent recorded in October. According to the first estimate by Eurostat, overall inflation in the euro area measured by HICP slowed down from 2.9 percent in October to 2.4 percent in November, and core inflation from 4.2 percent to 3.6 percent, according to HNB.
Indicators of current trends in overall and core inflation (quarterly rates of change on an annual basis) have been decreasing for three consecutive months. In November, the weakening momentum of overall inflation occurred due to a significantly weaker momentum of all major inflation components, which has decreased to a very low level.
Possible Disruptions Due to Geopolitical Tensions
The Croatian National Bank in its September 2023 projection expects the average annual inflation (measured by HICP) in 2023 to slow down to 8.8 percent (from 10.7 percent in 2022) and to 4.7 percent in 2024. The slowdown in inflation has been almost continuous throughout 2023 and has largely been a result of a strong reduction in energy price inflation and, to a lesser extent, food and core inflation (inflation that excludes food and energy prices from the calculation).
The continuation of this trend, according to HNB, is expected in the remainder of 2023 and during 2024, and it should reflect a decrease in core inflation and food price inflation, which remain at still elevated levels. Regarding food price inflation, a continuation of its slowdown is expected, in an environment of lower energy, fertilizer, and food raw material prices on the global market and normalization of supply chains. At the same time, the slowdown in core inflation may be of somewhat lesser intensity as this component (especially the service subcomponent) is more significantly influenced by strong growth in nominal wages.
Risks for achieving the projected inflation trend remain pronounced. Geopolitical tensions could still cause significant disruptions in the supply of energy and other raw materials on the global market and increase their prices. Furthermore, adverse weather conditions are an additional factor that could trigger an unexpected rise in food raw material prices as well as fruits and vegetables. The movement of food and energy prices has a significant impact on the perception of inflation and inflation expectations of households, therefore, in the described scenario, the continuation of the slowdown in household inflation expectations could be less pronounced than expected, which could result in greater and/or more persistent demands for wage increases.
Inflation could also be higher if the expected reduction in profit contributions to inflation does not occur, which would offset the impact of strong wage growth. Higher and/or longer-lasting inflation in countries that are major foreign trade partners could also result in higher consumer price inflation than previously expected. On the other hand, weaker economic growth and thus weaker demand, stronger effects of tightening monetary policy, and a more pronounced spillover of falling energy and other raw material prices on the global market to consumer prices of goods and services than currently expected are risks that could lead to inflation being lower than projected.