
—
—
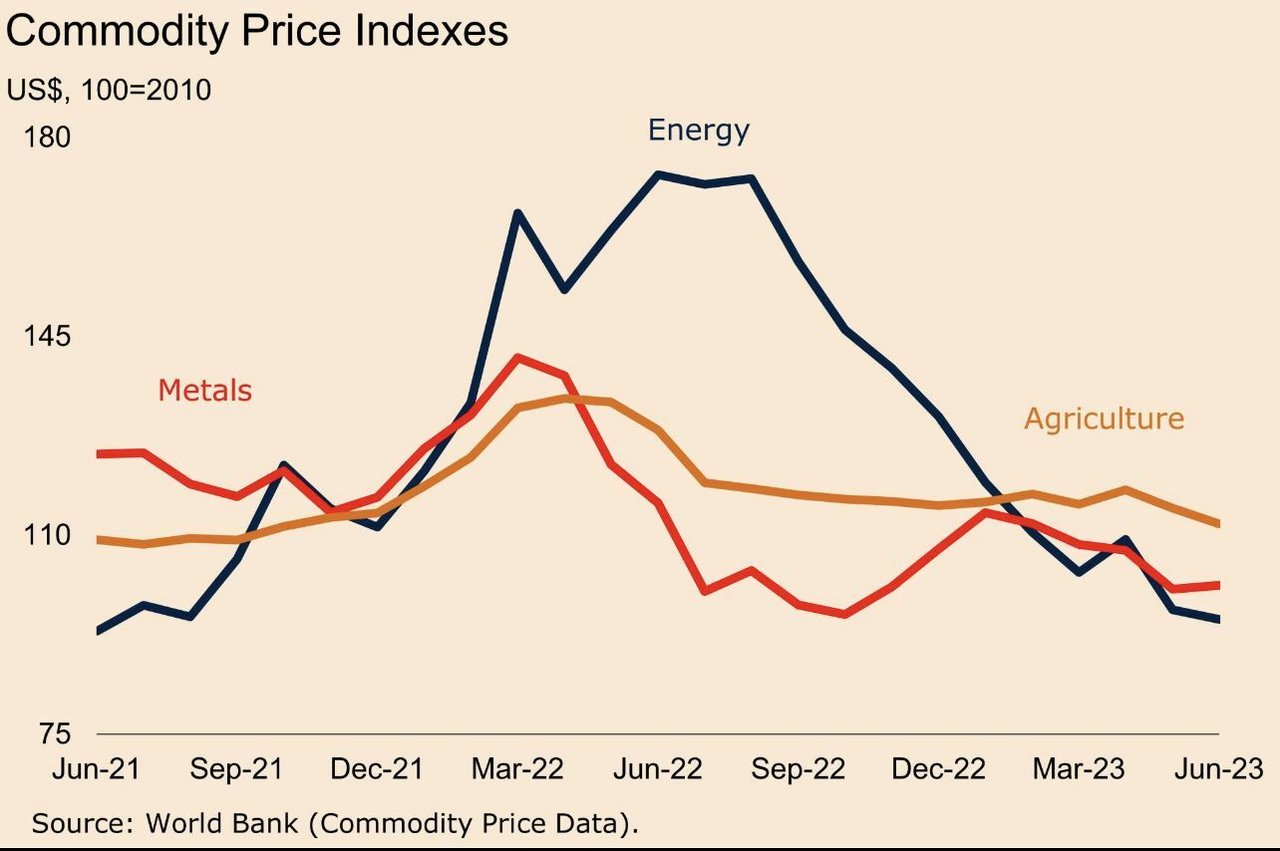
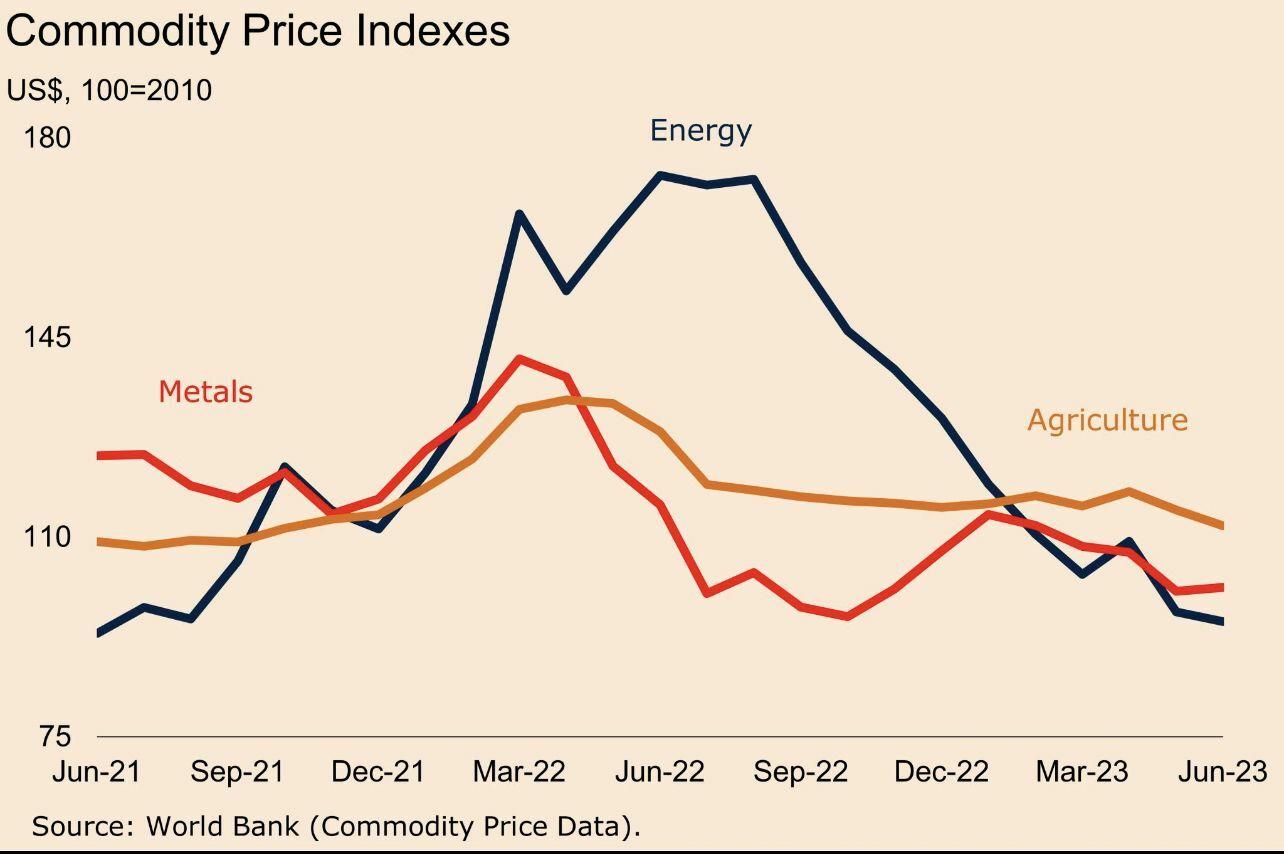
In the week behind us, the price of oil and coal increased, while the price of gas fell. The price of most metals rose, with a few exceptions such as iron ore and steel in China. Finally, agricultural commodity prices had similar movements, as for some goods the price increased, while for others it fell. However, considering that oil is a key commodity, we can say that generally the week behind us was positive for the movement of exchange-traded commodity prices.
Regarding some general indicators, the dollar index DXY is below 102 points, the S&P 500 index is above the level of 4,400 points, and the fear index VIX is above 15. The Goldman Sachs Commodity Index (GSCI) in the new week remains below 550 points, while the Bloomberg Commodity Index (BCI) is slightly above 102 points.
Today’s economy is characterized by persistent inflation, strict monetary policy, and increased volatility. BlackRock reports that core inflationary pressures show a certain persistence that is mainly related to mega-forces creating shortages in global production capacity. The consequence of these persistent inflationary pressures is that “central banks will have to maintain systematically more restrictive monetary policies than in the past in the coming months.”
In the markets, there is an 85 percent probability of a further increase in the interest rate (FED) by 25 basis points in July, partly due to the decisively aggressive tone recently used by American central bankers. The American yield curve has shown the largest inversion since 1981. Investors expect rates to rise soon, but believe that rising borrowing costs will ultimately harm the economy, forcing the FED to subsequently ease its monetary policy.
It is striking that the public debt of the United States has exceeded 32 trillion dollars for the first time, indicating a worrying fiscal trend and a likely consumption crisis. Despite recent cuts, the debt is expected to exceed 50 trillion dollars by the end of the decade. Regarding Europe, it is concerning that the number of corporate bankruptcies in Germany has significantly increased. Last month, more bankruptcies were recorded than in the previous seven years.
China has restricted the export of two vital metals (gallium and germanium) used in semiconductor production. This year, China has aggressively secured long-term LNG contracts with the aim of ensuring energy independence. Generally, China is using its resources to increase its involvement in global financial markets, with commodities becoming a central part of its strategy for greater global integration of the financial system. This can be very dangerous (in economic terms) for the rest of the (Western) world. It was recently revealed that the Minister of Energy of Saudi Arabia was invited by President Xi to consider pricing oil in digital yuan, backed by gold and other metals.
Still Several Risks with Gas
Brent crude futures prices are currently around $78/bbl after oil prices rose by more than four percent last week, as concerns about a global economic slowdown that could reduce oil demand outweighed prospects for reduced global supply from Saudi Arabia and Russia. Fresh data shows that factory deflation in the largest importer of crude oil, China, deepened in June, while consumer prices remained unchanged as the post-COVID recovery faltered.
In the U.S., still strong wage growth and a slight decline in unemployment are likely to keep the FED from raising interest rates later this month. Meanwhile, the U.S. administration plans to purchase about six million barrels of oil for the Strategic Petroleum Reserve, with receipts planned for October and November 2023. Natural gas futures prices in Europe were around €32/MWh, after a drop of about 10 percent in the first week of the month, which was the largest weekly drop since May, amid reduced demand and large inventories.
European gas storage is nearly 80 percent full, which is above the previous 10-year average fill level of only 60 percent. At the same time, demand for natural gas continues to decline in the EU, having fallen by 18 percent in the first quarter of 2023 and 22 percent in May, particularly in the industrial sector which recorded a decline of 19 percent in the first quarter and 25 percent in May. The EU has agreed to a voluntary reduction in natural gas demand by 15 percent by March 2024, while record LNG deliveries from the U.S. and increased supplies from Norway, Algeria, and Qatar have helped offset reduced flows from Russia.
However, there are still several risks, including the progress of Norwegian summer maintenance, competition from Asia for LNG, and the potential for increased demand as current prices are significantly lower than the level of €339/MWh reached last summer. Several Japanese companies are discussing long-term contracts for purchasing liquefied natural gas from Qatar. The Japanese have not signed an LNG contract with Qatar since 2014.
Prices Change Daily Just Like the Weather
Last year at this time, according to many newspaper articles at the time, it seemed that humanity was supposed to die of hunger? Since then, the FAO food index has been falling month by month, and is now 30 percent below the highest level in 2022. One just needs to allow the market to do its job (and have patience because such anomalies cannot be corrected overnight).
We have a big week ahead for commodity markets. Agricultural traders are awaiting two long-anticipated reports on Wednesday, both of which will shift futures prices: U.S. CPI inflation and the USDA WASDE report. The inflation report has significant implications for FED policy and the future trajectory of the U.S. dollar. The market expects inflation of 3.1 percent year-on-year, the lowest level since March 2021.
The WASDE report will include updated estimates for corn (higher) and soybeans (much lower) and could include significant changes in yield and export estimates. In addition, traders will monitor weather forecasts for the U.S. corn belt, the direction of crude oil, negotiations regarding the Black Sea corridor, and rising cash markets in South America. In short, we are facing a very volatile week with significant price shifts.
—
—
In the agricultural world, the main market mover is the weather, or rather the weather (un)conditions. It is once again confirmed that it is not in vain that the period from mid-June to the second half of August is also called the “weather market.” As weather models change (and with the development of technology, they change almost daily), so does the direction of price movements on exchanges (and partly in the physical commodity market). According to the latest model, lower and favorable temperatures are expected in the U.S. in the next 10 days, but the risk of a subsequent return of heat remains. As a result, the end of last week finished with almost all commodities in the red. The start of the new week began with profit-taking on created short positions ahead of expected reports this week.
In an ideal scenario, without climate and/or geopolitical incidents, the price of corn (DEC) on CBOT could fall below $5/bu, and soybeans (NOV) could exceed $14/bu. Technically speaking, quotas are what make the turning point, but geopolitics will not stand aside and watch. The grain export agreement from Ukrainian ports expires on July 17, and it now seems that the corridor may be extended amid the return of the Russian Agri bank to Swift!?
Copper Prices Soared
Regarding grains, the harvest period, along with continuous strong pressure from stocks at the end of the season in the Black Sea region, burdens prices in the near future. The difference between Russian and European prices is a key factor to monitor at the beginning of the season, in order to assess the attractiveness of Russian origin compared to Western European origin. In the EU, the latest wheat crop estimate is at 130 million tons, 2.7 million tons less than in the previous projection.
The corn crop estimate in the EU is currently at 61.2 million tons, 900 thousand tons less than in the June estimate. Wheat exports in the 2022/23 season were 31.14 million tons (vs 27.9 million tons in the previous season). Interestingly, of the total imports of 9.2 million tons, as much as 5.7 million tons were imported from Ukraine (compared to 2.5 million tons in the 2021/22 season). The same is true for corn. Total imports so far this season amount to 25.8 million tons, of which 14.5 million tons are from Ukraine.
Futures prices for copper have jumped above $3.7/lbs, supported by disappointing economic data that raised expectations regarding measures to stimulate the economy in China, and as declining inventories indicated a tighter market. The latest PMI survey revealed a slower expansion of the Chinese manufacturing sector in June, due to slow production and growth rates of new orders, a decline in employment levels, and weakening business sentiment.
Meanwhile, combined copper inventories in customs warehouses of LME, SHFE, COMEX, and China reached 225 thousand tons, representing a significant decline of 55 percent since March. This inventory level represents only three days of global copper consumption in 2022. Copper prices are expected to remain volatile in the coming months, influenced by fluctuations in the value of the U.S. dollar and investor sentiment regarding the Chinese manufacturing and construction sectors.


