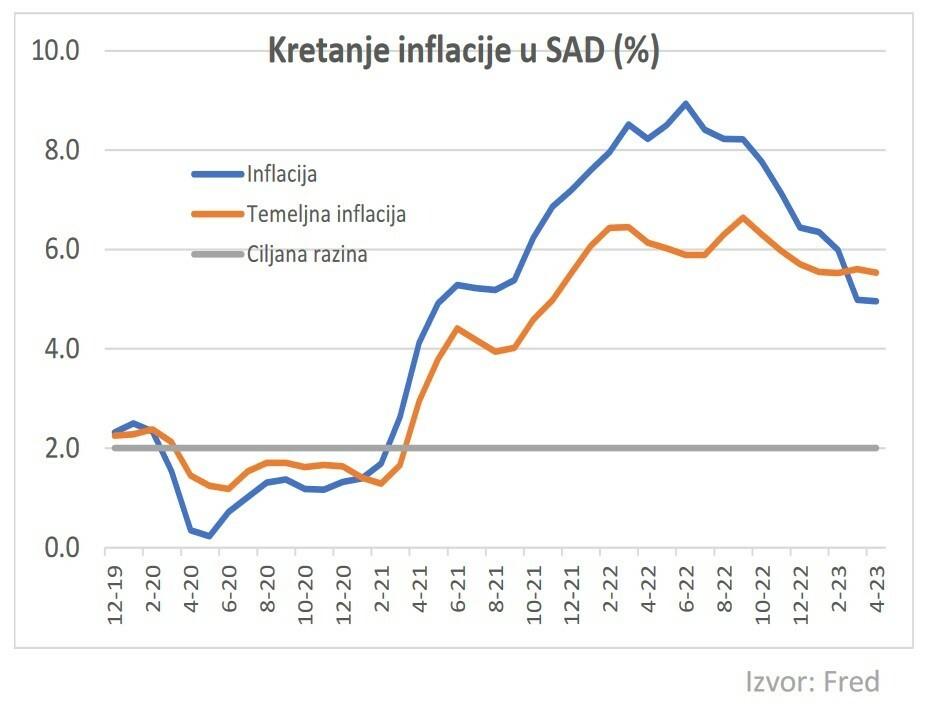
Consumer price inflation in the U.S. recorded a further (smaller) decline in the annual rate to 4.9 percent from 5.0 percent in April. However, despite peaking around 9 percent last summer, the monthly price rhythm remains (continuously) high even after the stabilization of energy prices and the cessation of food price increases, according to the Croatian Employers’ Association in its analysis this week.
Namely, the core inflation rate, which excludes food and energy prices and is more significant in terms of trend, has stabilized at an annual rate of around 5 percent for almost 12 months. Despite the easing of rental prices (40 percent of core inflation), price pressures are now strengthening again for some goods, such as used cars, which have increased by 4.4 percent monthly, not only due to relatively strong wage growth.
Inflationary pressures will continue to weaken for the rest of the year, but progress will be relatively slow, so inflation will ultimately remain above the Fed’s target level of around 2 percent. Meanwhile, uncertainty is peaking around the potential default (i.e., inability to meet obligations) of the U.S. government this summer, given the unsustainable trends in public finances.
—
—
In the first half of fiscal year 2023, up to the end of April this year, budget revenues are down nearly $300 billion year-on-year, while expenditures are about $270 billion higher. Despite full employment in the economy, the budget deficit has soared two and a half times to $928 billion.
Republicans are therefore rightly advocating for a 14 percent cut in spending (over a ten-year period); however, they propose cuts in several areas, such as subsidizing student loans and tax breaks for ‘green’ investments, which is politically sensitive for the Democratic Party.
Instead of political confrontation at ‘five to twelve’, it is in the interest of both political camps to suspend the statutory debt limit for a couple of months until September 30, which provides enough time for negotiations on the budget for 2024 on more rational grounds.
In Case of Default: Dark Scenarios
The Council of Economic Advisers to President Joe Biden assumes that in the event of a default, there would be a collapse of confidence similar to that of the global financial crisis of 2008, leading to a 20-30 percent cut in spending to be covered by revenues.
In the case of a short-term budget crisis, the same simulation estimates a loss of half a million jobs, while in the case of a deeper, prolonged crisis, the number of employed could decrease by as much as eight million.
The Fed’s maneuvering space for further easing monetary policy in conditions of high inflation is limited. The long-term consequences for financial markets and the dollar as the world’s reserve currency are difficult to assess.
How could the Fed position itself if a default truly occurs? Back in 2011, during a similar budget crisis when the statutory debt limit was raised just a few days before the default, the Federal Reserve presented an emergency action plan. According to it, the Fed would treat government bonds in default as if they had not ‘defaulted’ in its open market operations and discount window lending. In the event of disruptions in the money market and the REPO market, the Fed would likely begin purchasing Treasury bills to stabilize financial markets.
Purchasing bonds in default could prove politically controversial, as the central bank would be openly compromised under accusations of directly financing the government. One way to address these controversies would be simultaneous sales of ‘healthy’ bonds to prevent a suspicious increase in the Fed’s balance sheet.
It is clear that in the latter case, these are temporary measures in an emergency if there were to be a freeze in the bond market and serious problems in settling trades of financial instruments. Overall, the U.S. economy is ‘ripe’ for fiscal consolidation from the second half of this year, which only supports the widely accepted narrative of recession due to record tightening of monetary policy and worsening (commercial) financing conditions.
Additionally, problems in the segment of small and medium-sized banks (key for credit activity) along with the increasing appetite of authorities for regulating the financial industry only contribute to worsening financing conditions for a longer time than is currently estimated in popular commentary.