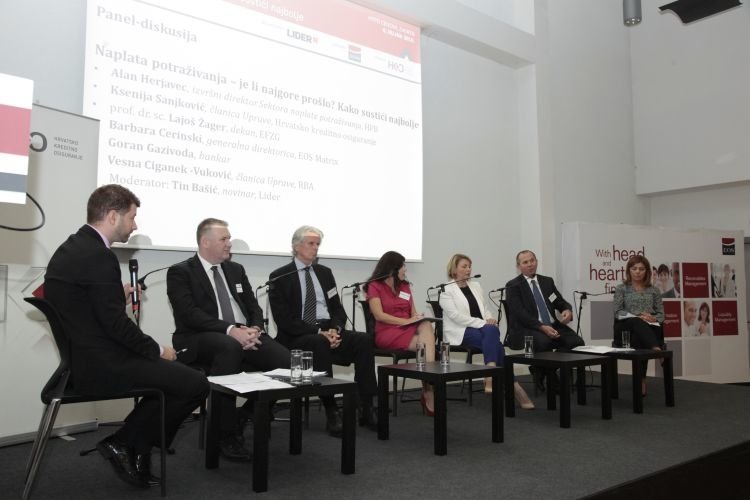
The panel discussion, the central part of Lider’s business meeting on debt collection, brought together eminent experts from the world of finance who shared their experiences, as well as theoretical insights, with around a hundred participants of this event.
At the round table titled ‘Has the Worst Passed? How to Catch Up with the Best’, participants included Barbara Cerinski (EOS MATRIX), Vesna Ciganek-Vuković (RBA), Alan Herjavec (HPB), Ksenija Sanjković (Croatian Credit Insurance), banker Goran Gazivoda, and Lajoš Žager, dean of the Faculty of Economics in Zagreb, with the role of moderator played by Lider’s journalist Tin Bašić.
– The payment deadline, as statistics show, is shorter, but the experience gained and lessons learned do not allow us to relax. We need to take small steps forward and not fall into the trap of enthusiasm, said Cerinski.
The Dean of the Faculty of Economics in Zagreb, after explaining all the theory and mechanics behind debt collection, recounted how his students see the Croatian word for compensation as ‘trampa’ (barter), but that barter is a good thing, Žager claims, money would never appear otherwise.
– We should spend less time discussing what led to non-payment of debts and more on building behavioral models for the future. We need to think about the economic literacy of citizens. At the faculty, we have a Financial Club Association, as well as a debate club, and children should be taught concepts such as credit and receivables as early as elementary school, believes Žager. He notes that although progress is evident – and Croatia is better positioned than Eastern Europe when it comes to debt collection – the balance sheet structures are not good. Whether the ‘worst has passed’ can only be determined when economic activities increase further.
However, the trends in payment habits among Croatians have not improved significantly, as evidenced by Ksenija Sanjković’s presentation.
– In our industry, where we deal with business entities, the trends are not positive. Neither in Croatia nor abroad. Compared to 2014, in 2015, the payment deadline increased by 5 percent, she warned.
Alan Herjavec also believes that positive trends in debt collection do not necessarily correspond with the situation in the economy, which is, after all, not that bright.
He asserts that banks always give clients enough time to reconstruct their balance sheets, although each case is specific, and believes that legal entities are much better acquainted with all possible solutions.
Banker Gazivoda admitted that banks should have better informed citizens about taking loans, which they have started to practice today. Likewise, Gazivoda, the initiator of Ebank d.d., the first ethical bank, mentions this form of banking as a necessary business model where there will be no service usage costs, nor account management or transaction fees, nor loans with currency clauses, and those who would not normally qualify for loans can always reach out for assistance.
Domestic banks have been highly capitalized all along, which means they could withstand significant shocks and remained stable during the trend of non-collection of debts, recounted Vesna Ciganek-Vuković. The negative trend is decreasing, and the share of bad placements is diminishing, but the problem is that there are no new placements. The investment crisis is at low levels, and as long as there is no demand for loans, we cannot say that the worst has passed, concluded a member of the Management Board of Raiffeisenbank Croatia.
This was followed by a one-on-one conversation with Tanja Pureta, director of Ramiro company, on the topic of Why Do We Get Into Debt?
– The biggest mistakes I and my surroundings have made mostly stem from a lack of thought, is a saying often heard in our office. It is impulsiveness that leads to unreasonable borrowing. It would be good to teach people to think about whether they really need what they want to borrow for. The purpose is not to have everything we want, but rather what we need, said Tanja Pureta, a specialist in organizational and industrial psychology in a conversation with Tin Bašić.
Pureta also presented her proposal for bankers to, in addition to informing clients about all risks before taking a loan, create a set of questions such as: Are you aware that this loan could lead you into debt? How would you behave in that case? How could you resolve it? This way, potential debtors would become more aware of the risks they are entering into instead of just being provided with information that they do not hear in a state of heightened excitement.
In the conversation, they also touched on the significant influence of society on borrowing. Peer pressure is present not only in childhood but also among entrepreneurs. For example, if a colleague has a larger office and earns better, the entrepreneur believes that by investing in a larger office, they will also earn more. However, they forget that one must first be in order to have, meaning they need to become an expert in their field to acquire what their colleague may have, concluded Tanja Pureta.