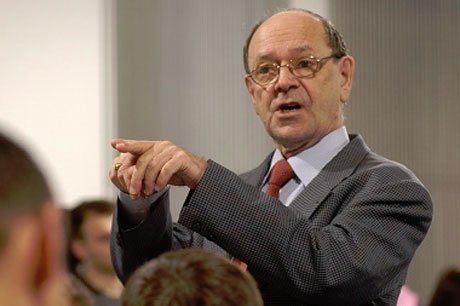
Renowned finance and strategy professor James Ellert received an honorary doctorate from the Bled School of Business last month and was also voted the best professor of the past year by students of the one-year and two-year MBA programs.
We spoke with Professor Ellert on this occasion about current events in the global economy.
• How do you comment on the inclusion of the Chinese yuan in the International Monetary Fund’s basket of reserve currencies (SDR, Special Drawing Rights)? Although some consider it a symbolic move, it is nevertheless an important decision that signals a shift in the global economy?
– China aspires to replace the dollar with the yuan as the primary global reserve currency. Reserve currencies have come and gone throughout history, and it favors the yuan as the next logical reserve currency. In the 17th century, the Dutch guilder emerged as a global reserve currency due to the success of the Dutch East India Company, and by the 1860s, the United Kingdom had become the world’s largest exporter, making the pound the world’s reserve currency. After a brief return to the gold standard in the 1930s, the US dollar took on that role at the end of World War II. Over the past 20 years, America has recorded significant trade deficits, while China has emerged as a new global exporter, which is why it believes it is time for the yuan to replace the dollar. However, due to Chinese intervention in foreign exchange markets in favor of Chinese trade, Western governments are likely to resist this.
On the other hand, Brazil and Russia advocate for the creation of a synthetic currency that would replace the US dollar. Such a currency, an expanded version of the SDR, would include all global currencies, with each weighted according to its contribution to global export trade. This would mean that the euro, dollar, and yuan would have the greatest weight, but unlike the SDR, this currency would become the standard for balancing trade among countries, rather than just an additional reserve currency as defined and maintained by the IMF. In this sense, the inclusion of the yuan in the SDR is recognition of China’s export strength and somewhat legitimizes China’s desire to participate in the global reserve currency or even an exclusive role as a substitute currency. The change is therefore more than symbolic as it signals recognition of the shift in global economic power from West to East.
• What will happen to the European recovery given the apparent slowdown in China and developing economies? European exports largely depend on demand in those economies.
– It is important to understand why China is slowing down and how the Chinese response to this could change the composition of Chinese imports from Europe, North America, and other developing economies based on natural resource exports. In 2011, China reached a GDP per capita of over five thousand dollars. This level of success is still very low by Western standards, but historical data over the past few centuries shows that it is difficult for an economy to maintain double-digit GDP growth after GDP per capita reaches three to five thousand dollars in purchasing power parity. It is therefore not surprising that there has been a Chinese slowdown in recent years, which would have happened even without the financial crisis of 2008. Chinese economic growth has continuously slowed from 22 percent in 2011 to around seven percent last year.
The GDP of a country is composed of three elements – consumption, investment, and government spending. China has noticed an excessive emphasis on the investment component of GDP and now has significant excess capacity in its industrial sector. The difference between this country and mature Western economies lies in the 34 percent share of consumption in GDP compared to 70 percent in America, 59 percent in Japan, and 57 percent in Germany. With the growth of the middle class of consumers and weaker export demand, Chinese decision-makers hope to revive GDP growth by focusing on strengthening domestic consumption as the new engine of that growth.
If China is successful in realizing this recovery plan, it will have implications for the composition of exports to China. Intentional slowing of state investments in the industrial sector will continue to reduce Chinese demand for raw materials and sophisticated industrial goods. At the same time, such a development could open opportunities for exporting quality consumer goods in the mid-price range or for foreign direct investment in the production of such goods in China. Value-based tourism could also benefit from this. As in the case of China, the European recovery is likely to require a more robust domestic expansion of growth alongside export-driven growth.
• How do you view the European Central Bank, has it done enough and can it do more to stimulate recovery?
– I think the ECB has done what it could to stimulate the European recovery. Following earlier initiatives in Japan (since the 1990s) and the US (after the last recession), the ECB has created an environment based on zero interest rates without stimulating inflation, but low interest rates are not enough to stimulate consumer and investor demand. Consumers are still deleveraging, while larger companies are accumulating cash, buying back shares, and cutting costs to improve short-term profitability instead of aggressively increasing their investment budgets for growth.
The Japanese experiment is particularly significant in this regard. After a quarter of a century of zero interest rates, Japan has been unable to create a longer period of strong economic growth. Even with unprecedented monetary easing, the recovery in the US has been mild and slow compared to other recent recoveries in the American business cycle. Policies of easy money may have prevented a global depression, but they are insufficient to stimulate a rapid recovery.