
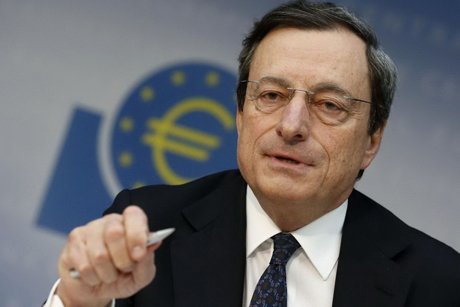
The conference of the President of the European Central Bank, Mario Draghi, for investors turned out to be a great disappointment, contrary to expectations and tradition.
Preparations were proceeding as expected: various verbal assurances from several prominent committee members, including the president, and there were also official statements suggesting that the central bank would take some serious actions.
– The President of the ECB was already accompanied by a reputation as a person who carefully manages market expectations through well-managed communication, leaving room for additional positive surprises. This was the thinking of market players, who believed that Mario Draghi shared the same attitude. However, after the surprise last Thursday, it seems that Mario Draghi has lost his magical communication wand, comments Michael Boye, a fixed income trader at Saxo Bank.
He also adds that the cut in the deposit interest rate by 10 basis points to minus 0.30 percent is already unprecedented, meaning the ECB charges banks 0.30 percent for holding money in accounts, and that the six-month extension of the government bond purchase program is indeed a serious easing of monetary policy.
However, the market hoped to receive much more, and investors were left with the impression that the German opposition within the ECB had won a ’round’. The latest strengthening of economic indicators such as the manufacturing PMI and industrial production undoubtedly does not favor Draghi. The price reaction was ruthless, and the 10-year German yield lost 20 basis points, the largest daily move in over three years, while market sentiment and risk assets also took a hit. The Chair of the U.S. Federal Reserve, Janet Yellen, surely received news from Europe with relief. A less aggressive ECB policy and a non-competitive euro are indeed a significant relief for U.S. companies, and this will undoubtedly boost morale at the central bank as they prepare for a meeting next week, where a decision is expected to be made to raise interest rates for the first time in nearly a decade, highlight Saxo Bank.


