
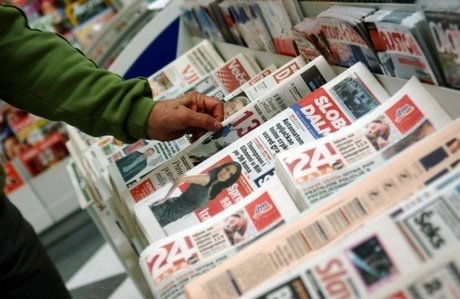
The Ministry of Finance has initiated a consultation on the draft proposal for amendments to the VAT Act, with the proposal being an increase in the intermediate VAT rate from 10 percent to 13 percent for all goods and services currently taxed at 10 percent, as well as equalizing the taxation of all newspapers and magazines, including daily newspapers, at a rate of 13 percent.
The Ministry has published a form for the assessment of impacts for the proposed amendments to the VAT Act on its website, thereby starting the consultation on this proposal which will last until November 8.
The proposal would increase the intermediate VAT rate of 10 percent, which currently applies to edible oils and fats, white sugar, baby food, water supply, hospitality and tourism services, concert tickets, certain newspapers and magazines, and cultural and artistic magazines, to 13 percent.
The proposal also includes that all newspapers and magazines be taxed at a rate of 13 percent, including all daily newspapers, except those that fully or partially contain advertisements or serve for advertising purposes. This aims to achieve uniform treatment in the taxation of newspapers, the Ministry of Finance explains.


