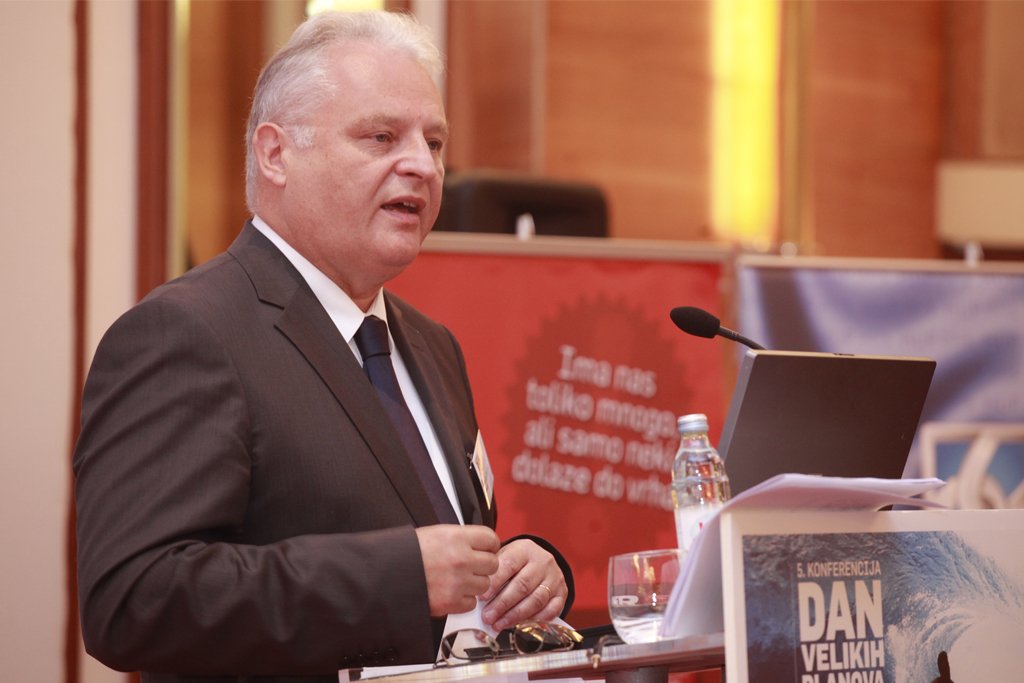
At the continuation of the Lider conference Day of Big Plans, in the panel Makroskop, there was more discussion about trends, business opportunities that entrepreneurs can find in the public sector, and the banking policy in 2014.
The path to recovery will be slow, there will be quite a few bad news, and the eurozone will have the hardest part of the recovery, emphasized Alistair Teare, director of Deloitte for Central Europe, speaking about global trends. He expects that the recovery will be led by the USA and China, while the eurozone will lag behind.
“A major achievement will be keeping the euro alive. The main hope for Europe is exports, both within the eurozone and outside it. The same applies to Croatia. Be more competitive and better, focus on what you have,” Teare advised.
However, optimism exists, sometimes more, sometimes less. The number one priority is to increase revenues in the markets, and the trend of reducing costs will continue. Another direction of optimism can be found in EU fund programs. It is important to access those funds, which largely go to research and development.
“Industrial policy is returning to focus, it is important for innovation and should focus on domestic markets. Start producing, bring innovations, establish small businesses… We need to encourage people to take risks and create an environment conducive to opening companies. The state-owned ones are inefficient,” concluded Teare.
Eurozone has gone through the worst
With trends and the situation in the region in 2014, Vladimir Gligorov, a professor at the Vienna Institute for International Economic Studies, added that the eurozone has gone through the worst. The fiscal balance in Germany is far more positive than in other regions. Germany has significant consolidation of public spending, which is one of the reasons for the significant slowdown in growth in the eurozone.
Regarding the future, Gligorov says that nothing particularly can be expected from fiscal stimulus, nor from public spending, and there is great uncertainty about the survival of the euro. An additional reason why significant recovery should not be expected in the peripheral EU countries is that with the change of the development model, lending from developed countries to less developed ones has been halted. In the last year, there has been a capital outflow from most Central EU countries, banks are deleveraging, etc. All this awaits a region that must reorient its entire growth strategy.
Regarding the sustainability of public finances, Gligorov says that the relationship between the interest rate and the growth rate is important. The current situation with the deficit is unsustainable and creates pressure on public spending and generates all other problems. The same situation applies to external debt.
He reiterated that for countries like Croatia, no growth faster than three percent is expected by 2015. He says that, more or less, we can talk about a lost decade. Why is that so?
“Private consumption whose growth cannot be particularly high, and secondly because the problem with the employment rate will be more permanent. In Croatia, there has been a significant reduction in the employment rate, and it will take quite some time to get these things in order,” predicted Gligorov, noting the importance of net exports which largely depend on the European environment and investments that are not recovering.