Home / Business Scene / Bankruptcy of Centar Bank Should Not Cost Taxpayers Anything

Bankruptcy of Centar Bank Should Not Cost Taxpayers Anything

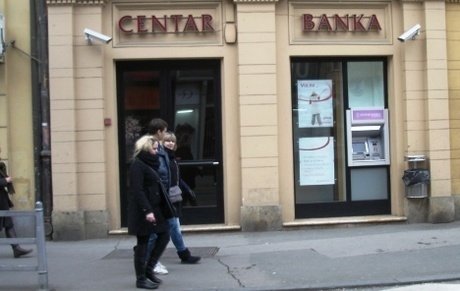
The potential bankruptcy of Centar Bank would cost more than that of Credo Bank, but the State Agency for Deposit Insurance and Bank Rehabilitation (DAB) states that it should not cost taxpayers anything, as there is enough available money in the Deposit Insurance Fund to compensate savers and clients.

At the end of last year, the Deposit Insurance Fund of DAB had 3.082 billion kuna available. According to data on DAB’s website, this amount represented the difference between total inflows and outflows in that fund, significantly more than 500 million kuna, which is estimated to be the amount of insured deposits in Centar Bank.

Moreover, the outflow of funds from the Fund in recent years, except in 2011 when Credo Bank went bankrupt, has been significantly lower than the inflow.

Last year, more than 550 million kuna flowed into the Fund, primarily from deposit insurance premiums, while the outflow amounted to 82 million kuna.

Since 1998 until the end of last year, DAB had to pay out a total of 4.355 billion kuna in compensation to savers and clients of failed banks and savings banks. By the end of last year, DAB had settled almost all obligations, according to data on DAB’s website.

During this period, a total of 26 Croatian banks and savings banks closed their branches.

Before this week’s proposal by the Croatian National Bank to initiate bankruptcy proceedings at Centar Bank, the last case of bankruptcy in the financial sector was the Split-based Credo Bank – in November 2011.

The total obligations for insured deposits at Credo Bank were determined to be 471.3 million kuna, so, according to initial estimates, the bankruptcy of Centar Bank would be somewhat more expensive for DAB.

However, it would not be the largest in the history of Croatian banking.

The largest amount of determined and paid obligations for insured deposits was recorded during the bankruptcy of Glumina Bank in mid-1999. The total obligations were 1.356 billion kuna.

Next was Gradska Bank, which closed its doors the same year, with total obligations for insured deposits determined at 961.2 million kuna.

A significant amount of DAB’s obligations for compensating savers and clients was also determined in 1999 at Županjska Bank, nearly 600 million kuna.


The highest number of bankruptcies of financial institutions in Croatia was recorded in 1999, when eight banks and savings banks closed their doors. In addition to Glumina, Gradska, and Županjska, these included Ilirija Bank, Komercijalna Bank, Promdei Bank…

Total obligations for compensation that year exceeded 3.07 billion kuna, while at that time deposits of individuals were insured only up to the amount of 100,000 kuna.

Today, however, the deposits of savers and clients of Centar Bank are insured up to the amount of 100,000 euros, in accordance with European regulations.

Another year ‘rich’ in bankruptcies of financial institutions in Croatia was 2001, when six of them closed their branches.

These were mostly savings banks, and the total obligations for the payment of insured deposits were incomparably lower than two years earlier, amounting to around 145 million kuna.

On the other hand, from March 2004 until November 2011, there were no bankruptcies of financial institutions that would require DAB’s intervention.

While at the end of the last century, bank bankruptcies were financed from the state budget – at the expense of taxpayers – this has not been the case for a long time.

DAB states that, according to the Deposit Insurance Act, the funds of the Deposit Insurance Fund may also consist of income from issuing its own bonds, borrowing from credit institutions, and even income from the state budget.

However, there have been no transfers from the state budget to DAB’s Deposit Insurance Fund since 2001.

-It is important to emphasize that the funds of the Republic of Croatia’s budget have not been used for the payment of insured deposits, after the payment of part of the bonds for financing deposit payments as a result of bank bankruptcies in 1999 and 2000- stated DAB.

Namely, all credit institutions in Croatia are included in the deposit insurance system and pay a certain premium into the Deposit Insurance Fund.

In recent years, the total premium amount that credit institutions pay into DAB’s Deposit Insurance Fund has been slightly above 400 million kuna annually.

