
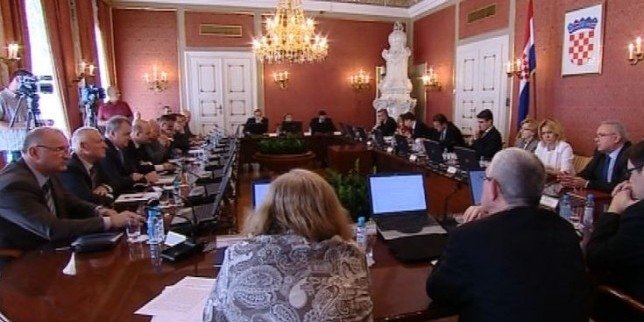
The government has accepted the proposal for the sale of 99 percent of the shares of Hrvatska poštanska banka and the sale of 40 percent of the shares and recapitalization of Croatia osiguranje.
Both companies are to be privatized through a public collection of offers from strategic investors. Finance Minister Slavko Linić stated that the government aims to maximize the revenue of Hrvatska poštanska banka, and the bank’s development cannot be ensured through the budget. There is no need for the government to retain any part in a bank that requires additional capital, and this way we will be able to choose a partner who can invest in the bank and its development, Linić explained. The tender for the sale of the minority stake in Croatia osiguranje will be open until the end of September, the minister said.
The proposal to amend the Consumer Credit Act, which introduces maximum allowable interest rates on housing and other consumer loans, has also been accepted. We have defined that after signing the contract, it is not possible to burden the user who signed the contract with additional fees, explained Slavko Linić. Prime Minister Milanović emphasized that this law was created to protect consumers and regulate relationships with banks. Be careful what contracts you sign, he warned.
The government has raised the excise duty on unleaded motor gasoline by 20 lipa per liter. Croatia is a country with the lowest excise duties on fuels in the EU. This is the reason that, in the desire to increase the state budget, we are raising these excise duties, stated the finance minister.
The government has sent a proposal to amend the Consumer Credit Act to the parliamentary procedure, which it assesses will strengthen the protection of consumer interests, clients of banks.
Finance Minister Slavko Linić emphasizes that the need for amendments to the law is clearly indicated by data on 300,000 blocked accounts of citizens and the increase in the share of non-performing loans in total housing loans to 12.5 percent.
According to the government’s proposal, fees related to approved loans must be linked to the actual cost of approving the loan, and the introduction of new fees after the conclusion of the loan agreement is prohibited.
The finance minister would define in more detail the issues related to fees by regulation. This, says Linić, avoids the possibility that fees contain hidden elements that raise the cost of the loan as well as the possibility of using unjustified fees.
The government also proposes the introduction of an obligation for banks to warn consumers in writing about the risks associated with changes in exchange rates and interest rates.
When contracting a variable interest rate, the government’s proposal defines the parameters that can be used as a basis for change – EURIBOR, LIBOR, NRS, or the average interest rate on deposits of citizens in the respective currency. This prevents banks from abusing the determination of parameters on the basis of which they will adjust variable interest rates, says Linić.
In order to avoid discrimination against consumers who have already concluded a loan agreement and for whom the parameters for changing the interest rate were not defined, the government proposes that even in such agreements, the bank must contract variable parameters, a fixed margin, and periods for interest rate changes as a basis for all future changes in the interest rate.


