
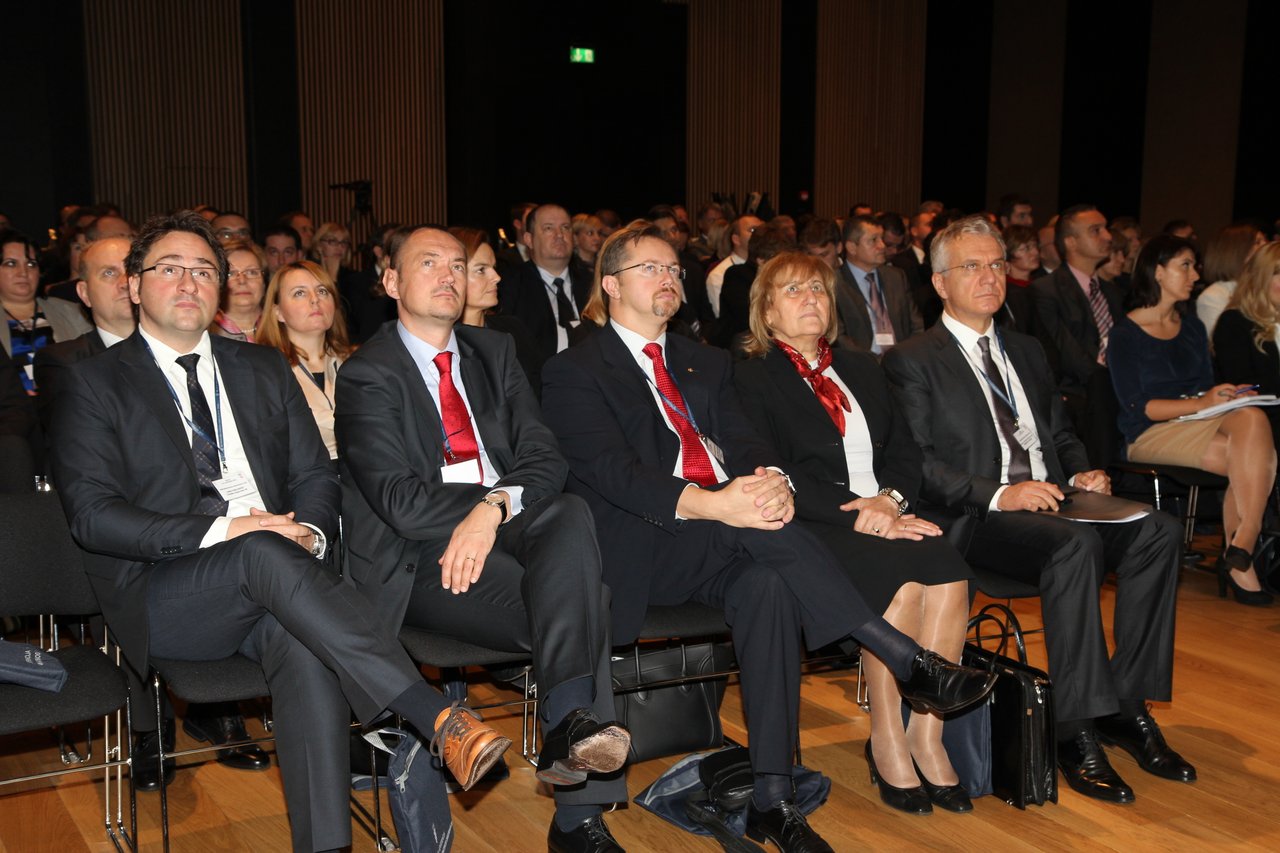
Aligning the Insurance Act with existing laws ahead of Croatia’s entry into the European Union was one of the main topics of discussion at the ongoing tenth conference ‘Days of Croatian Insurance’ in Rovinj.
Member of the Management Board of Hanfa, Gordana Letica, emphasized the importance of this and announced the adoption of a new Insurance Act for 2013, which will represent the regulatory framework for solvency and include mandatory licensing of insurance agents and brokers.
In Croatia, there were 23 insurance companies in 2002, while in 2012 this number slightly increased to 27. The insurance sector had 5,500 employees, and by 2012, this number rose to 11,300 employees, but Letica emphasizes that the increase mainly pertains to employees in the insurance acquisition sector.
– We in Croatia are still a bank-centric society and the growth of life insurance is poorly recorded – says Letica. Thus, the share of gross insurance premiums charged over a period of 10 years amounts to only 2.62 percent of the total gross national product.
– In ten years we have not moved from a standstill. Everything is still far from the average of European countries – notes Letica.
However, she reminds that until 2008 there was a recorded growth in the share of life insurance, which can be partially attributed to the pension reform as well as raising citizens’ awareness of the need for insurance. She adds that the influence of banks on the redistribution of market shares is definitely decisive and that there is still insufficient financial literacy and awareness of the need for insurance. Since 2008, this awareness, or rather the purchasing power of citizens, has fallen, and from 85 percent of the life insurance portfolio in 2012, this percentage dropped to 73 percent.
This is explained by the impact of the crisis, and she claims that this percentage drop is most visible in the auto casco insurance sector, which is mostly insured through leasing or loans if insured in this way. Since 2009, there have been no new vehicles and new premiums, leading to a portfolio spillover between insurers. Existing policyholders have stopped renewing their casco policies unless they have to, and there is constant competition among insurers, resulting in price dumping. Regarding the ratio of life to non-life insurance, it was 80:20 in 2002, while in 2011 this ratio looked like 75:25. Likewise, Letica emphasized the insufficient representation of almost non-existent rental insurance, critical illness insurance, or long-term care insurance.
– I have never understood the very small percentage of household insurance. Only one in four households in Croatia is insured, not to mention private liability insurance. Given that households are the largest asset a family possesses, I see a great opportunity for further growth in this segment – said Letica. Market liberalization, according to her, can significantly change the appearance of the insurance sector.
– This will be a kind of maturity test, and we will see if we can do something better in this area than was the case with auto casco – concluded Letica.
At the panel on the complementarity of public and commercial health insurance, Health Minister Rajko Ostojić also spoke, who immediately emphasized that the definition of the problem does not even exist on Wikipedia because ‘something that is a problem for one side does not necessarily mean a problem for someone else.’ It is said that a problem that money can solve is not a problem, but we must be aware that the time of pumping money into all segments has passed since 2008.
– I personally regret that HZZO did not exit the treasury back then. If it had, there would now be a strong insurance company in the Bismarck system. Healthcare is not part of the legal acquis. It has developed in various ways across Europe, such as Central European, Francophone, or Bismarckian. A pan-European health system in Croatia? I am convinced that it will not be established in the next two decades – said Ostojić.
He also emphasized the fact that 84 percent of health insurance is covered by HZZO, 0.6 to 0.9 percent constitutes supplementary insurance, while the rest comes ‘out of pocket’, so-called pocket money.
– It is incredible and incomprehensible how companies have not taken this segment more seriously. It is the line of least resistance. Every Croatian pays out of pocket the same as a citizen of Berlin, only there it goes through health insurance. Likewise, it is not fair to double tax retirees, and I plan to abolish that by the end of my term. Why should retirees pay that three percent even after their employment ends? I also think it is unnecessary for HZZO to enter the portfolio of private insurance. With the entry into the EU, better competition should, however, raise our quality as well. The fact is that aging is a luxury, and it costs. We definitely plan to reduce waiting lists, primarily due to overlaps – said Ostojić.
Director of the Croatian Health Insurance Institute, Siniša Varga, stated that the reduction of contributions has also reduced the labor cost of 70,000 workers in the Croatian health system.
Darko Cesar, CEO of Basler Insurance, agreed that there is stagnation in the insurance sector precisely due to the economic situation in the country. He added that if there is no increase in standards, it is hard to expect changes. CEO of Croatia Insurance, Kristian Podrug, expressed satisfaction with the minister’s promises to provide more opportunities for insurers. He added that there has been a significant drop in voluntary health insurance and that it is necessary to introduce so-called sick leave control, i.e., reduce waiting lists generated from sick leave.


